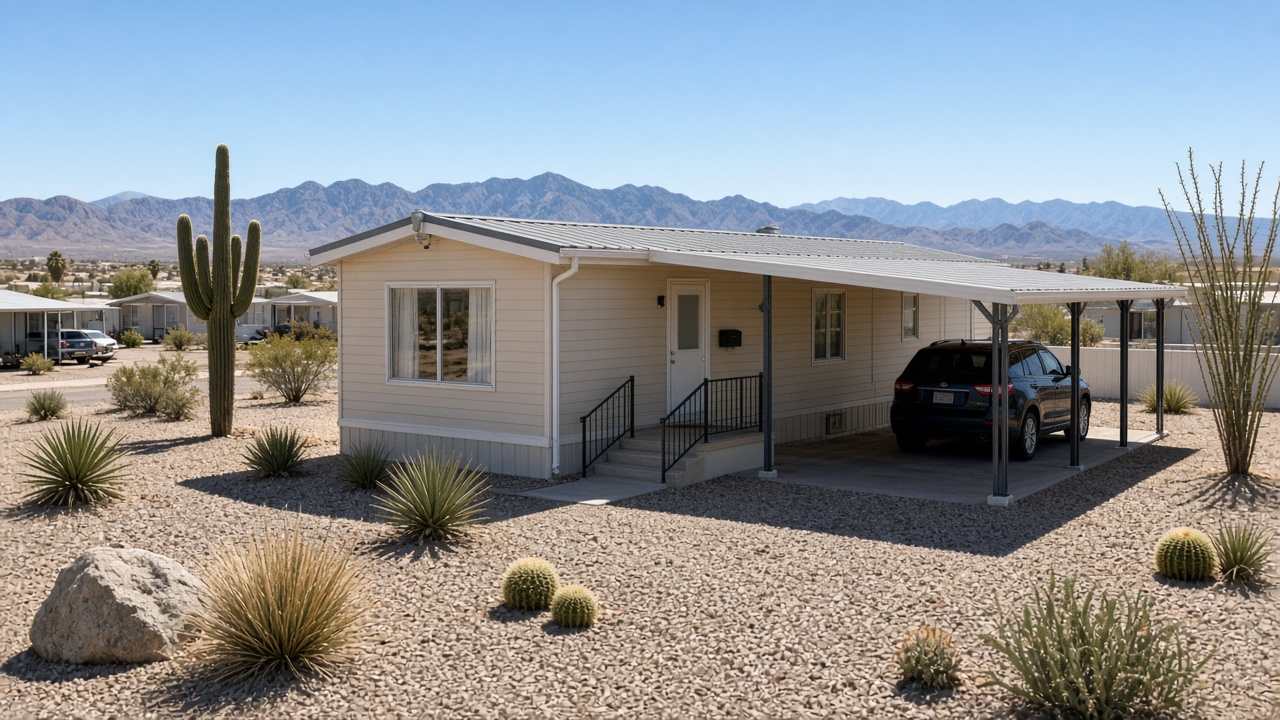
Mobile Home Insurance in Arizona: Manufactured Homes, Land-Lease Lots, and Park Models
Mobile home insurance in Arizona depends on three things before anything else: what kind of home you own, whether you own the land under it, and what has been added on since it was set. A 1990s manufactured home on a land-lease lot in Mesa, an older mobile home on owned acreage outside Tucson, and a park model in a winter resort each fit a different policy. Manufactured home insurance in Arizona is often written on specialty forms, not the standard homeowners policy.
We are Howard Castle Insurance, Independent Agents based in Gilbert. We shop manufactured-home and park model coverage across 40+ carriers, and only some of them write these homes. That is exactly why comparing matters. This article walks through the questions that shape these policies in Arizona.
Mobile, manufactured, or park model: why the label changes the policy
The words get used interchangeably, but carriers treat them differently. The type of home affects which policy form fits, which carriers will write it, and how a loss may be settled. Knowing what you own is the first step.
Here is the plain-language version:
- Mobile home: Usually refers to a factory-built home made before federal HUD construction standards took effect in 1976. Some carriers limit coverage on these older homes or do not write them at all.
- Manufactured home: A factory-built home built to the HUD code. It has a data plate and certification label that show it meets those standards. Most manufactured-home carriers focus here.
- Park model RV: A smaller unit built on a single chassis and designed mainly for seasonal or recreational living. It is often titled as an RV rather than a home.
Park models sit between RV and home coverage. Some carriers insure them on an RV-style policy. Others write them on a manufactured-home or seasonal dwelling form. Our RV insurance article covers motorhomes and travel trailers, and our RV insurance page has more on that side.
Before you call, find the year your home was built, the manufacturer, and the data plate or title information. Those details decide which carriers we can approach.
Land-lease community vs. owning the lot
In a land-lease community, you typically own the home and rent the lot underneath it. Your policy covers your home and belongings. The community generally insures its own common areas, such as the clubhouse, pool, and roads. When you own the lot, more of the property is yours to insure.
Arizona has many land-lease and manufactured-home communities, including a large number of 55+ communities in Mesa and Apache Junction. In those communities, a few insurance points come up again and again:
- Proof of coverage: Many parks ask residents to show proof of insurance, often including personal liability. Read your lease or park rules to see what is required.
- What the park insures: The community's policy usually protects the community, not your home or your belongings. Do not assume a park policy covers anything inside your space.
- Your lot improvements: Things you added to the lot, such as a shed, landscaping features, or a carport, may be your responsibility even though you do not own the land.
If you own the land, ask whether your policy covers the land improvements you added, such as a detached garage, fencing, or a well house. The answer depends on the carrier and the form.
Arizona rooms, carports, sheds, and add-ons
Many Arizona manufactured homes have additions: an enclosed Arizona room, a carport, an awning, a storage shed, steps, or a deck. These are where coverage questions often hide. Some policies cover attached additions as part of the home. Others treat them as other structures with a separate, smaller limit.
Questions worth asking about each addition:
- Is it attached to the home or freestanding?
- Was it built by the manufacturer, by a contractor, or by a previous owner?
- Is it included in the dwelling limit or under other structures?
- Is the limit high enough to rebuild it?
An Arizona room can add real living space and real value. If it is not counted correctly, a loss could leave a gap. Photos and any permits or receipts help us describe it accurately to a carrier.
If you are unsure what your current policy says about your additions, call our Independent Agents at (480) 500-7911 and we will walk through it with you.
Monsoon wind, tie-downs, and the age of the home
Monsoon wind is a major concern for manufactured homes in Arizona, especially for carports, awnings, and skirting. Carriers commonly ask how the home is anchored and how old it is. Both can affect eligibility and price.
Underwriting questions you may hear:
- Tie-downs and anchoring: How is the home secured to its foundation or piers? Carriers want to know it is properly anchored.
- Age of the home: Many carriers have age limits or extra requirements for older homes. Some will write older homes only on certain forms.
- Roof and updates: Has the roof been replaced or recoated? Have plumbing, electrical, or heating and cooling been updated?
- Skirting and additions: Are awnings and carports secured, and in good condition?
Wind damage, like a carport torn loose in a summer storm, is typically handled differently from water. Surface water and flooding are a separate topic, covered in our flood insurance article.
Replacement cost vs. actual cash value
On older manufactured homes, this may be the most important question on the quote. Replacement cost pays to repair or replace without subtracting depreciation. Actual cash value subtracts depreciation, which can sharply reduce a payout on an older home.
Some carriers offer replacement cost only on newer homes. Others offer it with conditions. Ask which settlement basis applies to the home and to your belongings, and compare quotes on the same basis.
Liability when you own the home but not the land
Owning a home on a leased lot does not remove your liability. If a guest trips on your steps or is hurt in your Arizona room, your policy's personal liability coverage is typically what responds. The park's insurance is generally for the park's own exposures.
That is one reason many communities ask residents to carry liability. Medical payments coverage is another piece worth asking about. It can help pay minor medical bills for a guest injured at your home, regardless of fault, within the policy terms.
Many residents in these communities also use a golf cart to get around. A cart is usually its own coverage question, so mention it when you call.
If you rent your manufactured home to someone else instead of living in it, you likely need a different policy. Our landlord insurance article explains that side.
Winter residents and homes left empty for the summer
Many manufactured homes and park models in Mesa, Tucson, and Yuma are occupied only in the cooler months. If your home sits empty for part of the year, your policy's vacancy or unoccupancy conditions matter. Many policies limit or exclude certain losses after a home has been empty for a set period.
The wording varies by carrier. Some carriers offer seasonal or secondary-home forms built for winter residents. Others may require someone to check on the home while you are away.
Before you leave for the summer:
- Ask how your policy defines vacant or unoccupied, and how long you can be away.
- Ask whether a seasonal-use form fits better.
- Arrange for a neighbor or service to check on the home.
- Take steps the carrier may ask about, such as shutting off water.
Letting your carrier know how you use the home up front is better than finding out about a vacancy condition after a loss.
How our Independent Agents shop manufactured-home carriers
We are Independent Agents, so we compare manufactured-home, mobile home, and park model options across 40+ carriers. Not every carrier writes these homes, and those that do have different rules on age, anchoring, settlement basis, and seasonal use. Shopping across many helps find a fit for your home.
Before you call, gather:
- Year, manufacturer, size, and data plate or title information
- Whether you own or lease the lot, and any park insurance requirements
- A list of additions, with photos
- Roof, plumbing, electrical, and HVAC update dates
- How many months a year you live in the home
Learn more on our home insurance page, or see our Mesa and Tucson service pages. Have a general question? Visit our FAQ or contact page.
Call Howard Castle Insurance at (480) 500-7911 to compare quotes from 40+ carriers with our Independent Agents.
FAQ
Is a park model insured like an RV or like a home in Arizona?
It can be either. Park models are often titled as RVs, and some carriers insure them on an RV-style policy. Others write them on a manufactured-home or seasonal dwelling form. The right fit depends on how the unit is titled, set up, and used.
Who insures my home in a land-lease community, me or the park?
You insure your home and belongings. The park generally insures its own common areas. Many parks also ask residents to carry personal liability and show proof of coverage.
Is my Arizona room or carport covered?
It depends on the policy. Some cover attached additions as part of the home; others treat them as other structures with a smaller limit. Ask how each addition is counted and whether the limit is enough to rebuild it.
Can I get replacement cost on an older manufactured home?
Sometimes. Some carriers offer replacement cost only on newer homes, and others offer it with conditions. Older homes are often written on actual cash value, so compare the settlement basis on every quote.
What happens to my policy if I leave my home empty all summer?
Many policies limit or exclude certain losses after a home has been vacant or unoccupied for a set period. Wording varies, and some carriers offer seasonal forms. Tell your carrier how you use the home before you leave.