Car Insurance in Phoenix, AZ: Freeway Commutes, Parking, and Glass Claims
Car insurance in Phoenix comes down to three questions most drivers never get asked: how many freeway miles you put on the car, where your car is garaged at night, and what happens when a rock hits the windshield on the I-10. Get those right and the policy fits the way you actually drive. Get them wrong and you can pay for coverage you do not use, or find a gap the day you need it.
We at Howard Castle Insurance, are Independent Agents based in Gilbert. We compare Phoenix auto insurance across 40+ carriers, so we can match your commute, your parking, and your glass needs to a carrier that wants that kind of driver. This article is about those Phoenix Metro insurance needs. If you want the basics of Arizona minimum limits, and why state minimums may not be helpful to you and your situation, our guide to car insurance in Gilbert already covers them.
Why a Phoenix car policy is shaped by miles, not just the ZIP code
Your ZIP code is only one piece of information that effects your rate. Carriers also rate based on the type of car you drive, how many miles you drive each year, what those miles look like, your driving record, and many other factors. A Phoenix quote that matches your real driving is usually more accurate than one built on a guess.
Two Phoenix drivers can live a few miles apart and still get very different quotes. One drives a long round trip on I-10 five days a week. The other takes surface streets to a job a few minutes away. The first car spends more time at freeway speed, in heavier traffic, and in more merges. Carriers see that exposure and price it differently, even when the cars and the drivers look alike on paper.
That is why we ask about your commute before we ask about deductibles. If your commute changed since you bought the policy, such as a hybrid schedule or a new job across town, tell us. A policy rated on an old commute may not reflect how you drive today and without accurate information on the policy, it can get cancelled by the insurance carrier.
For a more complete list of what moves an Arizona rate, see our article on average car insurance cost in Arizona. As we will not be discussing that on this page.
Commuting the Valley: I-10, I-17, the 101, and the 202
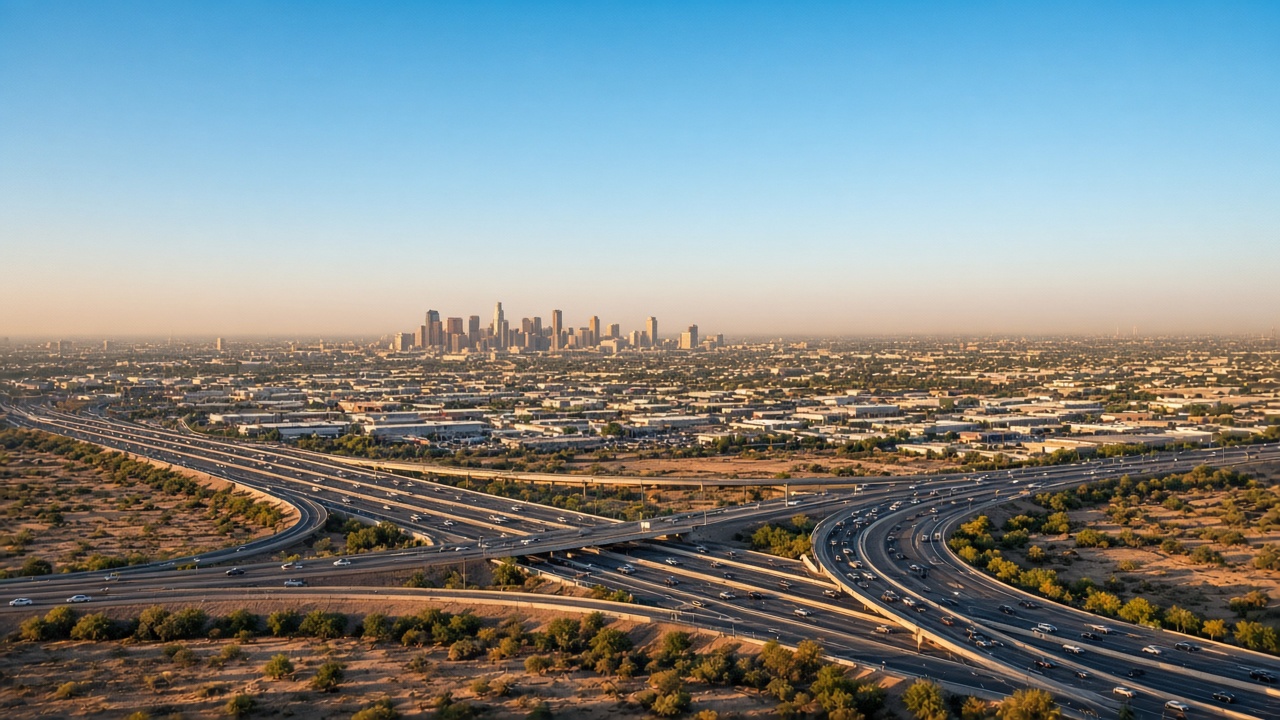
Phoenix Metro commutes run on a few big corridors. The I-10 and I-17 meet near downtown at the interchange locals call the Stack. Loop 101 rings the north and west sides, and Loop 202 carries traffic east toward the East Valley. If your daily drive runs through any of them, you are in steady, fast, merging traffic most days.
That traffic pattern matters for three important coverages:
- Liability pays for injuries and damage you cause to others. In dense freeway traffic, one mistake can involve more than one car.
- Collision repairs your own car after a crash, regardless of fault, minus your deductible.
- Comprehensive handles non-collision losses such as theft, vandalism, hail, and glass.
Weather adds to it. Summer dust storms can drop visibility on Valley freeways in minutes, and monsoon hail can damage a car that is parked or on the road. A crash in low visibility is generally a collision question. Hail damage is generally comprehensive. If a storm leaves water across a road, do not drive into it. Our flood insurance article explains why water is its own conversation.
Where the car is parked at night: apartment lots, street parking, and garages
Where you park overnight affects your comprehensive coverage more than most drivers expect. A car in a locked garage faces different risks than one in an open apartment lot or on the street. Carriers ask for the garaging address and parking location for a reason.
In central Phoenix, many drivers live in apartment complexes with open or carport parking. In North Phoenix, Ahwatukee, and Laveen, more households have an attached garage. Downtown and near Sky Harbor, some cars sleep in parking structures and others on surface lots. None of these is wrong. They are just different exposures.
- Open lots and street parking leave a car exposed to theft, break-ins, vandalism, and hail. Comprehensive is the coverage that responds to those losses.
- Carports help with sun and some hail, but they do not stop a break-in.
- A garage reduces several of those risks. Some carriers ask whether the car is garaged; others focus on the address.
If you finance or lease, your lender likely requires comprehensive and collision. If you own the car outright and park in an open lot, dropping comprehensive to save money deserves a careful look first, as your car will not be covered in those situations. Review your declarations pages to see how a specific carrier treats your parking situation, because carriers do not all weigh it the same way.
Want help sorting out your setup? Call our Independent Agents at (480) 500-7911 and tell us where the car stays overnight.
Rideshare and delivery driving in Phoenix
A personal auto policy often excludes or limits coverage while you are logged in to a rideshare or delivery app. That gap can show up even before you accept a ride or an order. If you drive for Uber, Lyft, DoorDash, or a similar app in Phoenix, tell your insurer.
The rideshare or delivery company usually carries its own insurance, but it works in phases and often require the driver's insurance to pay first. The coverage while you are waiting for a request is generally different from the coverage once you accept a trip or have a passenger or order in the car. The waiting period is where many drivers find the thinnest protection.
Some carriers offer a rideshare endorsement that can help fill that gap on your personal policy. Availability and terms vary by carrier and by the type of driving you do, which is one reason shopping across many carriers helps. We will tell you plainly if a carrier will not cover app driving.
If the driving goes beyond occasional app work, such as a car you use mainly for business, a courier route, or a vehicle titled to a business, it may belong on a commercial policy instead. Our article on commercial auto insurance in Arizona explains where that line usually falls.
Windshields, rock chips, and glass coverage
Glass damage is a familiar headache for Phoenix drivers. Freeway gravel, construction zones, and summer heat can turn a small chip into a long crack. Glass is generally handled under comprehensive coverage.
Many carriers in Arizona offer a full-glass option on comprehensive. With it, a covered windshield repair or replacement may carry no deductible, or a separate glass deductible from the rest of your comprehensive. Wording and availability vary by carrier, so it is worth reading the glass language on any quote side by side.
Is it worth it? It depends on how you drive. If you put a lot of freeway miles on the car, a separate glass option may make more sense than for someone who drives a few miles on surface streets. Newer vehicles with cameras and sensors mounted near the windshield can also make replacement more involved, which is worth weighing. Please note that replacing the glass on your insurance counts as a claim.
A few practical tips:
- Get small chips looked at early. A repair is usually simpler than a replacement.
- Ask whether your policy lets you choose the glass shop.
- If your car has driver-assist features, ask whether recalibration is part of a covered glass claim.
Uninsured drivers and the limits we look at first
When we review a Phoenix policy, uninsured and underinsured motorist coverage (UM/UIM) is one of the first things we check. It protects you and your passengers when the at-fault driver has no insurance or not enough to cover the injuries they caused. In a metro area with this much freeway traffic, you may want that protection in place, before we talk about trimming the price.
Arizona sets minimum liability limits for every driver, and many drivers carry only those minimums. We explain what the minimums are, and why we usually talk about higher limits, in our car insurance in Gilbert guide. Here, the point is simple: if another driver's limits are low, your own UM/UIM coverage can step in to pay for your injuries.
If you are required to carry an SR-22 after a violation, our SR-22 insurance article walks through that process.
How our Independent Agents compare Phoenix quotes across 40+ carriers
We compare Phoenix Metro car insurance quotes from the 40+ carriers we can shop with, so you are not limited to one company's appetite or pricing. Different carriers favor different drivers, whether that is a long-commute driver, a rideshare household, or a car parked on the street or only write commercial policies.
Many Phoenix drivers call us after a renewal jump with a single-company policy. We look at what changed and whether another carrier fits better. We cannot promise a lower price, but we can show you real options side by side.
Before you call, have these ready:
- Your current declarations page
- Drivers Licenses for all drivers in the household, vehicles, and VINs
- Where each car is parked overnight
- Your rough annual mileage and commute route
- Whether anyone drives for a rideshare or delivery app
You can read more about our auto insurance options or our Phoenix insurance services page. Questions first? Visit our FAQ or contact page.
Call Howard Castle Insurance at (480) 500-7911 to compare quotes from multiple carriers with our Independent Agents.
FAQ
Does my Phoenix car insurance cover me while I drive for Uber, Lyft, or DoorDash?
Often not or not fully. Many personal auto policies exclude or limit coverage while driving for Uber, Lyft, DoorDash, etc. The app company's insurance works in phases, and the waiting period is often the thinnest. Some carriers offer a rideshare endorsement. Tell us if you drive for one of these companies so we can find a fit and get you covered.
Does it matter to my insurer if I park on the street or in an apartment lot?
It can. Carriers rate the garaging address, and some ask whether the car is kept in a garage. Open lots and street parking leave a car more exposed to theft, vandalism, and hail, which are comprehensive losses. How much it matters varies by carrier.
Is a zero-deductible glass option worth it for Phoenix freeway driving?
For many freeway commuters, it is worth pricing. Many carriers in Arizona offer a full-glass option on comprehensive, though wording varies. Compare the cost of the option against your normal comprehensive deductible. And remember, glass replacement through insurance counts as a claim.
Why did my Phoenix quote change when I moved from Ahwatukee to central Phoenix?
Your garaging address is a rating input, and so is how you park. A move can change the address rating, factoring in how people drive in your area, your commute miles, and whether the car rests in a garage or an open lot. Each of those factors can move the price up or down.
How many carriers do your Independent Agents compare for Phoenix drivers?
We compare quotes from 40+ carriers. Not every carrier will write every driver or vehicle, but shopping that many gives Phoenix drivers more than one option.