Commercial auto insurance in Arizona is the contract for a vehicle a business puts on the road for work. A personal auto policy is written for household driving. On standard personal insurance, commercial use, delivery, and hauling tools or goods for hire sit outside that contract. That is a policy-form issue, not a statute, and it is not identical on every form. The line that matters is the use exclusion on the policy you already have. I suggest you take a moment to look at your current policy to see what is covered and what is not.
We are Gilbert-based Independent Agents at Howard Castle Insurance. We shop multiple carriers to find you the best coverage for the best rate. Commercial auto is a specialty market, so that list does not mean every carrier will write every town, every vehicle weight, or every driver. The wider commercial picture sits on our business insurance page. This article will focus on the work vehicles.
A household car is a different contract. Our guide to car insurance in Gilbert is for personal use. It does not cover a work truck that leaves for a job site.
Personal auto policies typically exclude business use of the vehicle. The usual break is not "you have a job." Driving a household car to a W-2 workplace is often still personal use. The difference shows up when the vehicle is used to haul tools, delivers goods, or is how the business moves from site to site. We did not invent an exclusion for that. It is most likely already on your coverage form.
The name on the title does not settle the use. Single-member business often title the truck to the owner and still uses it for work. Personal title, business miles. Insurance focuses on the use of the vehicle, not the title.
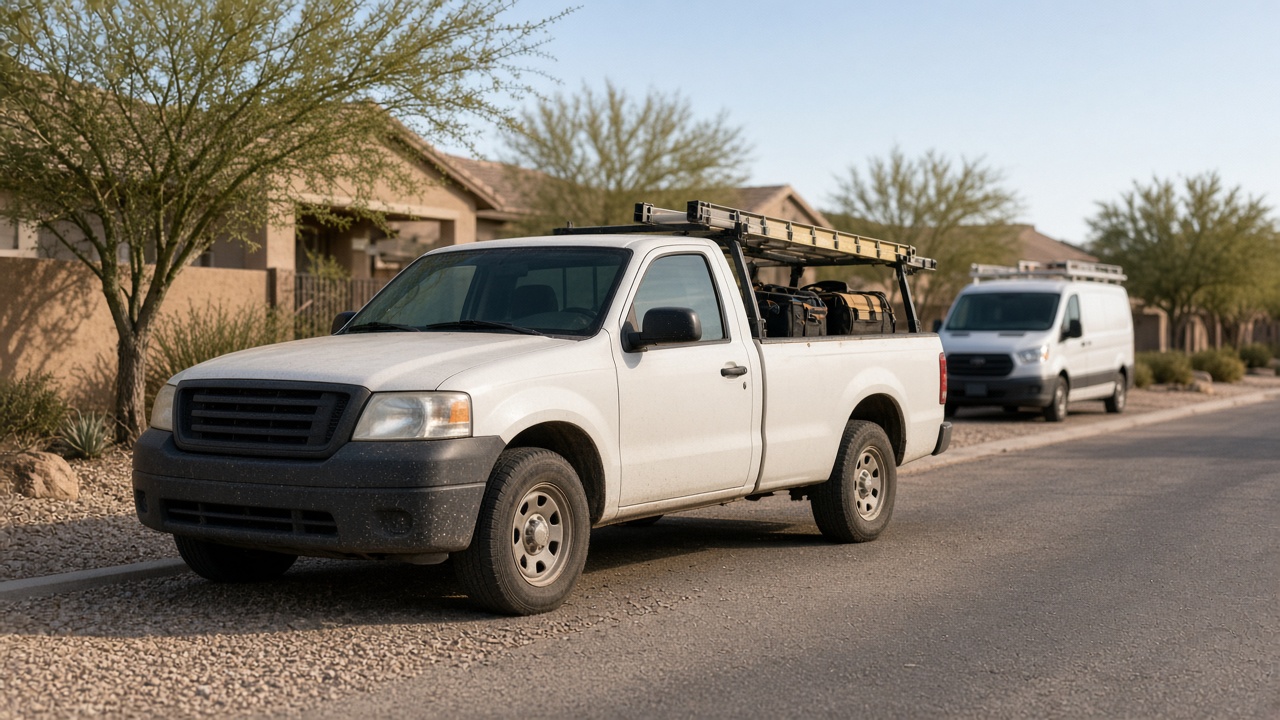
A contractor takes the truck to a Chandler job site in the morning and a Phoenix site later the same day. A Mesa van that carries a helper and the day's equipment is work use of that van, not a family errand that happens to include a ladder. A light delivery route inside Phoenix is business use, even when the business is one person and one van.
Business auto insurance in Arizona is the plain name for that commercial form. Commercial truck insurance in Arizona is the same question when the vehicle is a work truck. Commercial auto insurance in Phoenix is this contract when the delivery or the job site is in the city, not a separate policy for a Phoenix address.
If the only vehicle in the household is a personal car, for personal use start with auto insurance.
A scheduled vehicle is one the business owns or keeps and lists on the policy. The work truck, and a van or two the company operates, belong on that list when they are used for work. Do not assume an unlisted vehicle is covered because the business owns a similar one.
Hired auto is a vehicle the business does not keep. A rental pickup for the week the truck is in the shop is the plain example. Non-owned auto is a vehicle the business does not own, but someone uses it for the business. The usual case is an employee taking their own car for a supply run or a trip between a Mesa job and a Chandler job. The same question comes up in real-estate work when a personal car is how the business gets to showings. We are not saying every employee's car needs a hired and non-owned policy. It is a common gap to ask about when people use their own cars for work. The employee's personal policy may exclude that business use too. Ask before you assume either reach out for a review of your policy.
When you call, tell us the truck or van you own, the vehicle you rent, and whose personal car runs the errands.
Liability and physical damage do different jobs.
Liability responds when a covered driver is responsible for someone else's injury or for damage to someone else's property. It does not repair your truck, and it does not replace what was loaded in it. This article does not state an Arizona commercial liability minimum. A general contractor or a property manager may write a limit into the job. That number belongs to the contract. It does not mean it is the state minimum.
Physical damage on the vehicle is covered by comprehensive and collision. Where the form includes comprehensive, that part can respond to theft of the truck or van, fire, and certain other non-collision losses. Collision can respond when the vehicle itself is damaged in a crash. If a lender or a lease requires both, make sure you ask to complete.
Tools, equipment, and materials in the bed or the cargo area are often not fully covered by the auto policy. A loss that takes what was loaded in the truck can sit outside the settlement for the vehicle. Bring a list of what stays in your work vehicles. A vehicle that carries people and equipment needs both answers: liability for the road, and a yes or no on the equipment.
Whoever drives belongs on the application. The owner who runs a Gilbert truck to Chandler. The employee who takes the Mesa van. A helper who drives only on busy weeks still drives on those weeks. Commercial markets underwrite drivers. A carrier can accept the business and still decline a driver, a longer radius, or a heavier truck. We do not publish a weight cutoff, as there are so many variables to be considers. Tell us about the vehicle and who drives it or has access to the keys.
Radius is part of the same fact. Job sites among Gilbert, Mesa, and Chandler are not the same operation as a truck that runs into Phoenix most days, and neither is hauling past the state line. Insurers rate the radius you drive. Shopping 40+ carriers does not mean each of them will write that radius, that weight, or those drivers.
A general contractor or a property manager may ask for a certificate before the truck enters the site. They may want to be an additional insured. They may want primary wording. Those words come from that job. We do not keep a city licensing minimum for Gilbert, Mesa, Chandler, or Phoenix, and this article will not invent one. Read the insurance section of the contract, then call with that page. We line the certificate up to what the job asked for.
If the operation needs a state or federal filing, that is a separate compliance question. This article does not give filing steps. Confirm with the Arizona Department of Transportation or FMCSA whether a filing applies.
Our pages for Gilbert, Mesa, Chandler, and Phoenix are about local context. They do not change the commercial auto requirements.
Commercial auto is only the vehicle insurance. It does not stand in for the rest of a business insurance set.
An employee injured on the job is the workers' compensation conversation. A customer who slips at the shop is general liability. A business owners policy packages property and general liability. It is not the contract for the truck, the van, or a hired auto. Those products are already explained on general liability insurance in Arizona and workers' compensation insurance in Arizona. If you have questions about those coverages, go to those pages.
Call us at (480) 500-7911, Monday through Friday, 8:00 a.m. to 5:00 p.m. MST, to compare commercial auto quotes from multiple carriers. Have the year, make, and model, how each vehicle is titled, who drives, how far the trucks go, whether you rent a vehicle or send anyone out in a personal car, and any certificate language a general contractor has already sent. If you still have a personal policy on the truck, keep the declarations nearby so we can review the use exclusion with you.
We will let you know if an insurance carrier will or will not write the radius, the vehicle, or a driver. Leaving the truck on a personal form that typically excludes the work is not a workaround.
If you have any other questions, you can start on our contact page or the FAQ. For a review or comparison, call (480) 500-7911.
Typically, no, when the truck is used for the business. Hauling tools, delivering goods, and driving between job sites are the uses to look for in the exclusion. A personal name on the title does not undo it, and the wording is not the same on every form. Household cars stay on the auto insurance side. The Gilbert guide is only a personal-use contrast: car insurance in Gilbert.
Hired auto applies to a vehicle the business rents or borrows for work, such as a rental truck while yours is down. Non-owned auto applies to a vehicle the business does not own when someone uses it for the business, often an employee's car on an errand between sites. It is a common gap to ask about. It is not a rule that every employee car must be added. That driver's own policy may exclude the business errand too.
Often, not in full. Comprehensive and collision, when they are on the policy, address the truck or van. Tools, equipment, and materials loaded in it are frequently outside that settlement. But an endorsement can be added to cover the tools in the event of theft or an auto accident.
If a vehicle is used for the business, yes. General liability is for certain premises and operations claims, such as a customer injured at the shop. It is not the policy for the truck. A business owners policy bundles property and general liability and is still not the vehicle contract. Employee injuries belong on workers' compensation insurance in Arizona. The business premises is discussed on general liability insurance in Arizona.
Read the job's insurance section first. Note any request for additional insured status, any request for primary wording, and the limit the contract writes down. That limit is the job's figure, not an Arizona commercial auto minimum. Have the vehicles and drivers already described on the policy. Call (480) 500-7911 with that page. We match the certificate to the job and do not invent a city licensing minimum.
We shop top carriers including


Have questions? Need a quote? We're here to help. Reach out and let's find the perfect coverage for you.
Mon-Fri: 8:00 AM - 5:00 PM MST
Saturday & Sunday: Closed
Gilbert, Arizona
Proudly serving all of Arizona
Get a free quote from 40+ carriers in minutes. No obligation, no pressure—just great coverage options.
Get Your Free QuoteFill out the form below and we'll get back to you as soon as possible.