Commercial auto insurance in Arizona is the contract for a vehicle a business puts on the road for work. A personal auto policy is written for household driving. On the usual personal form, commercial use, delivery, and hauling tools or goods for hire sit outside that contract. That is a policy-form issue, not a statute, and it is not identical on every form. The line that matters is the use exclusion on the policy you already have. Read it.
We are Gilbert-based Independent Agents at Howard Castle Insurance. We shop 40+ carriers. Commercial auto is a specialty market, so that list does not mean every carrier will write every radius, every vehicle weight, or every driver. The wider commercial picture sits on our business insurance page. This article stays on the work vehicle.
A household car is a different contract. Our guide to car insurance in Gilbert is for personal use. It does not answer a truck that leaves for a job site.
Personal auto policies typically exclude business use of the vehicle. The usual break is not "you have a job." Driving a household car to a W-2 workplace is often still personal use. The break shows up when the vehicle hauls tools, delivers goods, or is how the business moves from site to site. We will not invent an endorsement name for that exclusion. It is on your form.
The name on the title does not settle the use. A single-member business often titles the truck to the owner and still uses it for work. Personal title, business miles.
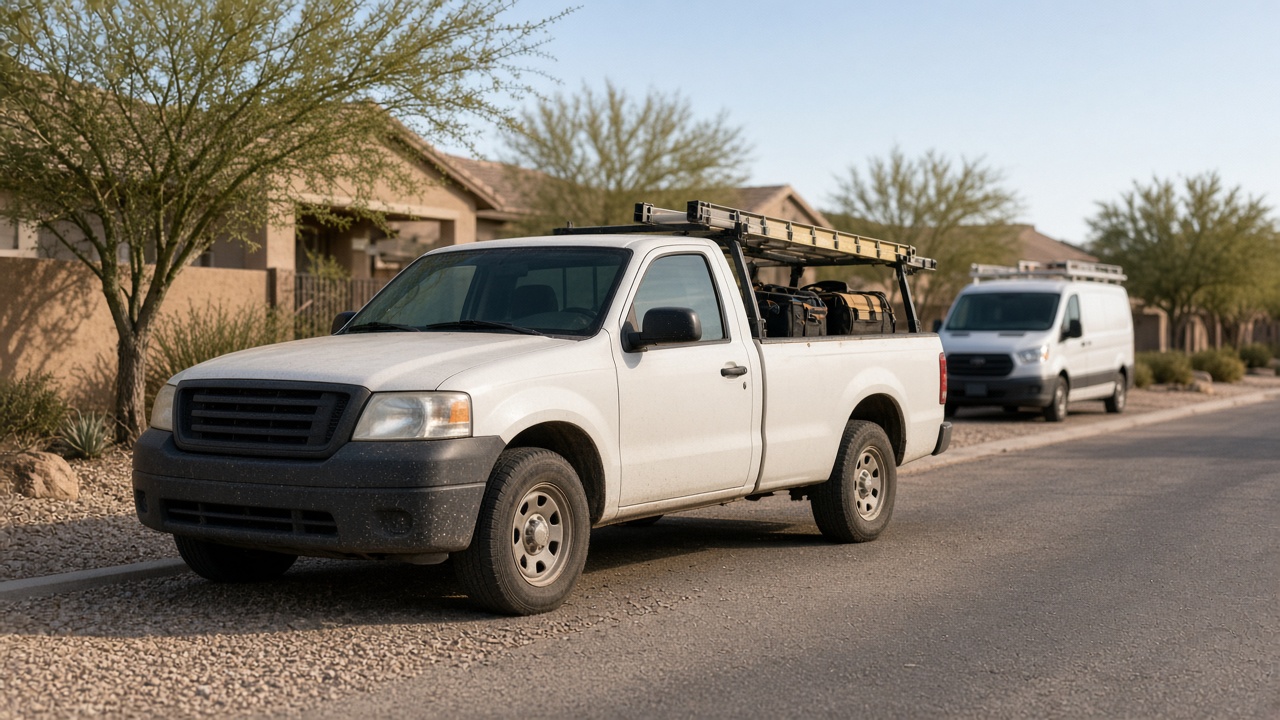
That driving is ordinary in the East Valley, and the policy is still an Arizona policy, not a Phoenix-only page. A Gilbert contractor takes the truck to a Chandler job site in the morning and a Phoenix site later the same day. A Mesa van that carries a helper and the day's equipment is work use of that van, not a family errand that happens to include a ladder. A light delivery route inside Phoenix is business use even when the business is one person and one van.
Business auto insurance in Arizona is the plain name for that commercial form. Commercial truck insurance in Arizona is the same question when the vehicle is a work truck. Commercial auto insurance in Phoenix is this contract when the delivery or the job site is in the city, not a separate policy for a Phoenix address.
If the only vehicle in the household is a personal car, start with auto insurance. That page does not move a work truck onto a personal form.
A scheduled vehicle is one the business owns or keeps and lists on the policy. The work truck, and a van or two the company operates, belong on that list when they are used for work. Do not assume an unlisted truck is covered because the business owns a similar one.
Hired auto is a vehicle the business does not keep. A rental pickup for the week the truck is in the shop is the plain example. Non-owned auto is a vehicle the business does not own when someone uses it for the business. The usual case is an employee taking their own car for a supply run or a trip between a Mesa job and a Chandler job. The same question comes up in real-estate work when a personal car is how the business gets to showings. We are not saying every employee's car needs a hired and non-owned policy. It is a common gap to ask about when people use their own cars for work. The employee's personal policy may exclude that business use too. Ask before you assume either contract responds.
This is not a fleet desk. Tell us the truck you own, the van you rent, and whose personal car runs the errand.
Liability and physical damage do different jobs.
Liability responds when a covered driver is responsible for someone else's injury or for damage to someone else's property. It does not repair your truck, and it does not replace what was loaded in it. This article does not state an Arizona commercial liability minimum. A general contractor or a property manager may write a limit into the job. That number belongs to the contract. Confirm it there before anyone treats it as law.
Physical damage is comprehensive and collision on the vehicle itself. Where the form includes comprehensive, that part can respond to theft of the truck or van, fire, and certain other non-collision losses. Collision can respond when the vehicle itself is damaged in a crash. If a lender or a lease requires both, use the requirement they wrote down.
Tools, equipment, and materials in the bed or the cargo area are often not fully solved by the auto policy. A loss that takes what was loaded in the truck can sit outside the settlement for the vehicle. Bring a list of what stays in it. A van that carries people and equipment needs both answers: liability for the road, and a yes or no on the equipment.
Whoever drives belongs on the application. The owner who runs a Gilbert truck to Chandler. The employee who takes the Mesa van. A helper who drives only on busy weeks still drives on those weeks. Commercial markets underwrite drivers. A carrier can accept the business and still decline a driver, a longer radius, or a heavier truck. We do not publish a weight cutoff. Tell us the vehicle and who holds the keys.
Radius is part of the same fact. Job sites among Gilbert, Mesa, and Chandler are not the same operation as a truck that runs into Phoenix most days, and neither is hauling past the state line. We rate the radius you drive. Shopping 40+ carriers does not mean each of them will write that radius, that weight, or those drivers.
Our pages for Gilbert, Mesa, Chandler, and Phoenix are local context. They do not change the commercial auto form.
A general contractor or a property manager may ask for a certificate before the truck enters the site. They may want to be an additional insured. They may want primary wording. Those words come from that job. We do not keep a city licensing minimum for Gilbert, Mesa, Chandler, or Phoenix, and this article will not invent one. Read the insurance section of the contract, then call with that page. We line the certificate up to what the job asked for.
If the operation needs a state or federal filing, that is a separate compliance question. This article does not give filing steps. Confirm with the Arizona Department of Transportation or FMCSA whether a filing applies.
Commercial auto is the vehicle contract. It does not stand in for the rest of a business insurance set.
An employee injured on the job is the workers' compensation conversation. A customer who slips at the shop is general liability. A business owners policy packages property and general liability. It is not the contract for the truck, the van, or a hired auto. Those products are already explained on general liability insurance in Arizona and workers' compensation insurance in Arizona. We will not re-explain them here.
Call us at (480) 500-7911, Monday through Friday, 8:00 a.m. to 5:00 p.m. MST, to compare quotes from 40+ carriers. Have the year, make, and model, how each vehicle is titled, who drives, how far the trucks go, whether you rent a vehicle or send anyone out in a personal car, and any certificate language a general contractor has already sent. If you still have a personal policy on the truck, keep the declarations nearby so we can read the use exclusion with you.
We will say when a market will not write the radius, the vehicle, or a driver. Leaving the truck on a personal form that typically excludes the work is not a workaround.
Other questions can start on our contact page or the FAQ. For this comparison, call (480) 500-7911.
Typically, no, when the truck is used for the business. Hauling tools, delivering goods, and driving between job sites are the uses to look for in the exclusion. A personal name on the title does not undo it, and the wording is not the same on every form. Household cars stay on the auto insurance side. The Gilbert guide is only a personal-use contrast: car insurance in Gilbert.
Hired auto applies to a vehicle the business rents or borrows for work, such as a rental truck while yours is down. Non-owned auto applies to a vehicle the business does not own when someone uses it for the business, often an employee's car on an errand between sites. It is a common gap to ask about. It is not a rule that every employee car must be added. That driver's own policy may exclude the business errand too.
Often, not in full. Comprehensive and collision, when they are on the policy, address the truck or van. Tools, equipment, and materials loaded in it are frequently outside that settlement.
If a vehicle is used for the business, yes. General liability is for certain premises and operations claims, such as a customer injured at the shop. It is not the policy for the truck. A business owners policy bundles property and general liability and is still not the vehicle contract. Employee injuries belong on workers' compensation insurance in Arizona. The premises boundary is general liability insurance in Arizona.
Read the job's insurance section first. Note any request for additional insured status, any request for primary wording, and the limit the contract writes down. That limit is the job's figure, not an Arizona commercial auto minimum. Have the vehicles and drivers already described on the policy. Call (480) 500-7911 with that page. We match the certificate to the job and do not invent a city licensing minimum.
We shop top carriers including
Have questions? Need a quote? We're here to help. Reach out and let's find the perfect coverage for you.
Mon-Fri: 8:00 AM - 5:00 PM MST
Saturday & Sunday: Closed
Gilbert, Arizona
Proudly serving all of Arizona
Get a free quote from 40+ carriers in minutes. No obligation, no pressure—just great coverage options.
Get Your Free QuoteFill out the form below and we'll get back to you as soon as possible.