Flood Insurance in Arizona: Monsoon Water, Washes, and the Homeowners Gap
Flood insurance in Arizona is a separate policy for water and mud that comes from outside and moves over the ground. It is not a homeowners policy with a monsoon endorsement added to it. On most homeowners forms, flood is excluded. If a summer storm pushed water over a Phoenix street, across a low Mesa lot, or through a wash behind a Gilbert or Chandler house, "water damage" on the home policy is not usually covered.
We are Gilbert-based Independent Agents at Howard Castle Insurance, and we shop multiple carriers. Flood is a specialty policy. Not every company that writes a home policy also writes private flood coverage, and a flood policy is not something we add onto a quote automatically.
Our home insurance page is about standard homeowners policies. A mention there of monsoon weather is not a promise that a homeowners quote includes flood. If you are looking for homeowners insurance in Chandler, check this page out.
What a homeowners policy usually does with water
On most homeowners forms, the contract is built for things that happen to the building, not for water that arrives across the ground. Overflow, runoff, water moving through a wash, or a rising river is generally excluded. The declarations in your policy control the loss.
A sudden pipe break is often a different question and is often covered by your homeowners policy. Water that was already in the plumbing is not the same as water that ran in from the yard. A slow seep is not the same as a break, but coverage for that can usually be added to a standard home policy.
Rain through a wind-opened roof is often different too. The way the water enters the home is the question. Sewer or drain backup is a another issue. On many forms these can be added by an endorsement, as they are not surface water and not a roof opening. Flood water comes from water that overruns the ground. All can happen on the same afternoon and still be separate causes of loss.
Dwelling limits and roof settlement belong on the home insurance page. Monsoon water on the ground is generally outside the home policy and is covered by a separate flood policy. Any lender requirement for flood insurance can be addressed. If you are interested in discussing this valuable coverage, please reach out to us at 480-500-7911.
A roof leak and surface water are not the same claim
A hard summer storm, water in the street, and a water damage from a pipe are not one covered peril. A rainfall total or a news story about a storm does not decide if your damage is covered.
Rain through a roof happens when wind or a falling tree branch opens roofing, flashing, or a skylight and rain falls inside. On many homeowners forms that is storm damage is covered as it is not surface water. The path the water took is what the claim looks at.
A burst pipe is from a supply line that lets go inside the house. That cause of loss is different on the home policy, not caused by rain runoff. A monsoon on the calendar does not change the plumbing.
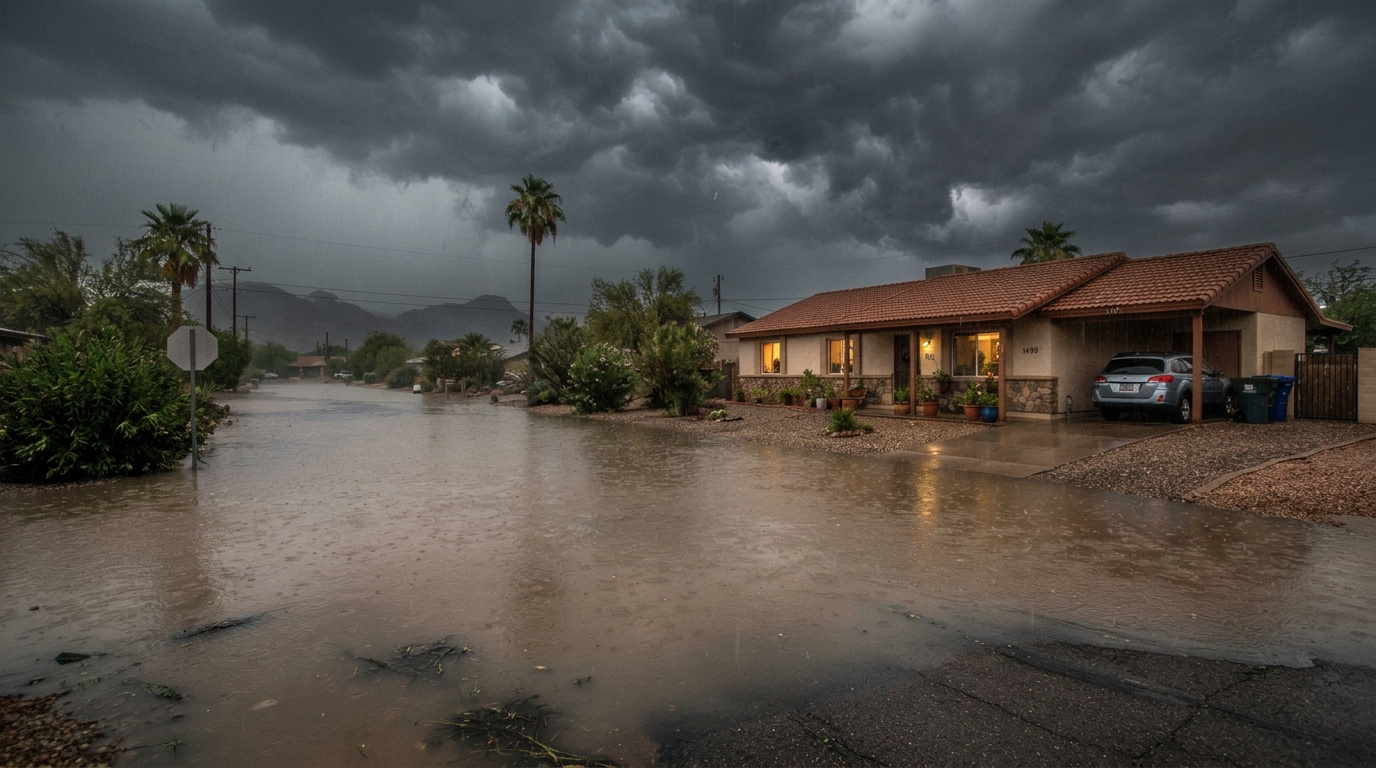
Surface water is storm water that leaves a street, a lot, or a wash and crosses the ground into the house. That is the flood exclusion on most standard homeowners forms. Water can pond in the street and never come inside. If it came in over the ground, the coverage for the damage to your home would be found in a flood policy.
Washes and low spots in the East Valley
Washes in Phoenix, Mesa, Gilbert, and Chandler stay quiet for long stretches. They can look like a gravel channel, a low path behind a block wall, or a dry ditch between lots. In a strong summer storm they carry water runoff. A low pad or a side yard that slopes toward that channel can take water even when the wash looked dry at noon.
Distance from a river is not the test. A house several blocks from any river can still take water off a low lot or a corner that ponds. A flood map is a starting point for that parcel. It is not a yes or no to whether you should purchase a flood policy.
Our pages for Phoenix, Mesa, Gilbert, and Chandler are for local policy questions. None of them assigns a flood zone. A lender may require flood insurance for a specific loan and a specific property. Bring what the lender sent, and we can confirm it with the lender.
NFIP and private flood policies
There are two ways to buy flood coverage. One is a policy through the National Flood Insurance Program. The other is private flood insurance from a company that writes it. Neither is included in your standard homeowners insurance policy. A homeowners carrier insures the roof, walls, floors and can provide liability coverage for specified causes of loss.
Waiting periods are common, and the number of days depends on the program. We can check the current rule for the property you want coverage on, which matters if you are closing or a lender set a deadline.
On a quote, we look at whether it is an NFIP policy or a private flood policy, and whether it covers the building, the contents, or both. Insuring the structure does not automatically insure the furniture. Basement areas, if the house has any, and additional living costs can be limited. Additional living expense on a homeowners policy does not follow a flood loss on its own. By shopping multiple carriers is how we compare the policies those companies write.
The price of the flood policy comes from the location of the property and underwriting factors.
Renters and landlords
If you rent, the landlord's building policy is not a policy on your furniture, and a renters policy is not flood insurance for the building. A standard renters form is generally built for perils such as fire and theft, not for water that came over the ground. Furniture damaged that way is its own flood question, including in a first-floor apartments in Phoenix, Mesa, Gilbert, Tempe, Queen Creek, San Tan Valley or Chandler.
Renters insurance and renters insurance in Arizona explain the renters policy. Like standard homeowners policies, standard renters insurance is not flood policies.
If you own a rental, a landlord property form is still not a flood policy. The building can carry homeowners insurance and still have the surface-water gap. Flood coverage on a rental is a separate placement.
How to call
Call (480) 500-7911, Monday through Friday, 8:00 a.m. to 5:00 p.m. MST. Have the address, whether you own or rent, and whether a lender has asked for flood insurance. If you already have a homeowners or renters policy, keep the declarations nearby so we can read the water language.
We will let you know whether the quote is for a standard homeowners form, an NFIP flood policy, or a private flood policy. Other questions, feel free to call us at 480-500-7911, go through our contact page or the FAQ.
FAQ
Does homeowners insurance in Arizona cover flood or monsoon runoff?
Generally, no. On most homeowners forms, water from outside that moves over the ground, including monsoon runoff, overflow, a wash, or a rising river, is excluded. A sudden pipe break or rain through a wind-opened roof is often a different question. "Water damage" on the declarations page is not flood coverage.
If rain comes through my roof during a monsoon, is that a flood claim?
No. Rain that enters because wind opened the roof is often a storm-damage question on the homeowners policy, as it is not caused by surface water. A monsoon does not turn that opening into a flood. The path the water took is what the insurance adjuster looks at when filing a claim.
Do I need flood insurance if I am not next to a river?
Maybe. Distance from a river is not the test. Summer storms put water in streets, washes, and low lots in Phoenix, Tempe, Mesa, Queen Creek, San Tan Valley, Gilbert, and Chandler. A map is a starting point for the parcel, not a citywide determination of yes or no. A lender may require flood insurance for a specific loan. Confirm that with the lender for that property.
What is the difference between an NFIP policy and private flood insurance?
Both provide flood coverage. An NFIP policy is the National Flood Insurance Program. A private flood policy is a company's own form. Either can insure building and contents separately, and either can limit basement coverage and additional living costs. Waiting periods are common, and the number of days to wait depends on the program. Not every carrier among the 40+ we shop offers private flood. But we do have several that offer it.
Does renters insurance cover flood damage to my furniture?
Generally, no. A renters policy is not flood insurance, and it does not insure the building. Furniture damaged by surface water needs its own flood conversation. For more questions about Renters insurance and renters insurance in Arizona check out these pages.